Car Rental Insurance in Malaysia: What Does It Actually Cover?
Key Takeaways
- Car rental insurance in Malaysia covers certain accident-related risks, but you may still need to pay an excess.
- Third-party motor insurance is legally required, while additional rental protection depends on the company’s terms.
- Collision Damage Waiver (CDW) reduces your liability for eligible vehicle damage but does not always eliminate it.
- Flood damage, tyres, negligence and unauthorised drivers may be excluded from standard coverage.
- Additional insurance is worth considering when the potential excess exceeds what you can comfortably afford.
Car rental insurance in Malaysia can cover third-party liabilities, accidental vehicle damage and theft, depending on the policy and rental agreement. However, having insurance does not automatically mean you pay nothing after an accident. You may still face excess charges or costs excluded from the coverage.
This is where renting a car becomes confusing. A booking might advertise insurance as included, yet the rental agreement could still make you responsible for thousands of ringgit.
Before paying for additional protection, it helps to understand what is covered, how excess charges work and whether upgrading your insurance is worthwhile.
Read More: Which Is Better for Travel: Car Rental vs Using Your Own Car in Malaysia
What Does Car Rental Insurance in Malaysia Cover?
Car rental insurance generally covers specific accident-related risks, but the level of protection depends on the rental company and insurance package.
Here are the common types of coverage available when renting a car in Malaysia.
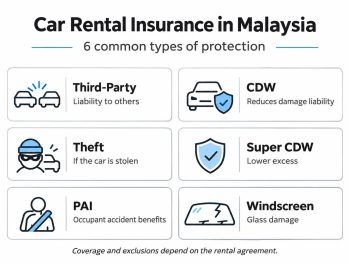
Third-Party Insurance
Third-party motor insurance can cover legal liabilities involving other people, including injuries, death and property damage.
However, Malaysia’s minimum legally required insurance, known as Act cover, primarily addresses third-party death or bodily injury. Broader third-party motor policies can also cover property damage, depending on their terms.
For example, if you accidentally collide with another vehicle, the rental car’s insurance may cover eligible third-party claims.
However, third-party insurance alone does not necessarily cover repairs to your rented vehicle.
Collision Damage Waiver (CDW)
CDW reduces the amount a car rental company can charge you for eligible damage to its vehicle.
Although commonly described as insurance, CDW is generally a contractual waiver or limitation of your financial liability.
For example:
- Vehicle repair cost: RM5,000
- Applicable CDW excess: RM1,500
- Your maximum eligible damage payment: RM1,500
For eligible damage, the waiver limits your payment to the applicable excess. The rental company’s insurance or protection arrangement handles the remaining covered cost, subject to the agreement.
However, excluded damage and additional fees may still be charged separately.
Theft Protection
Theft Protection limits your financial responsibility if the rental vehicle is stolen.
However, failing to secure the keys, report the theft or follow the rental agreement could affect your coverage.
Personal Accident Insurance (PAI)
PAI provides specified benefits following an accident involving covered occupants.
Depending on the policy, benefits may include medical expenses, permanent disability or accidental death compensation.
Before purchasing PAI, check whether your existing medical, personal accident or travel insurance already provides similar protection.
Is Car Rental Insurance Mandatory in Malaysia?
Third-party motor insurance meeting Malaysia’s legal requirements is mandatory, but purchasing additional rental protection packages is not necessarily required.
Under Section 90 of the Road Transport Act 1987, motor vehicles must have valid insurance or qualifying security covering specified third-party risks.
The minimum legally required Act cover primarily protects against liability involving third-party death or bodily injury. Broader policies may also include third-party property damage and protection for the insured vehicle.
The Ministry of Transport Malaysia provides information about the legislation governing motor vehicle insurance requirements.
However, there is a distinction between:
- Mandatory motor insurance: The vehicle must have valid insurance that satisfies Malaysian legal requirements.
- Optional rental protection: Additional packages such as CDW upgrades, excess reduction or personal accident insurance.
Some rental companies include CDW in their rental rates or make certain protection packages compulsory under their own terms.
Therefore, always confirm what is included before signing the agreement.
What Is Car Rental Insurance Excess?
An excess is the amount you may have to pay for an eligible damage or theft incident, up to the limit stated in your rental agreement.
It is one of the most important figures to check when comparing car rentals.
Some rental companies apply an excess to each separate incident rather than once per rental.
Excluded damage, administrative fees and other charges may also remain payable.
How Much Would You Pay After an Accident?
Suppose you rent a car for four days under the following hypothetical conditions:
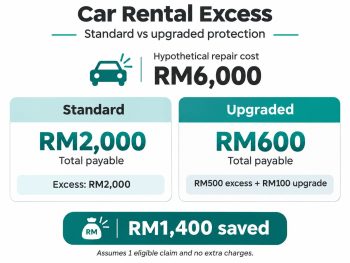
The upgraded coverage costs RM25 per day.
RM25 × 4 days = RM100
If one eligible accident occurs, the upgrade reduces your assumed total expense from RM2,000 to RM600, saving RM1,400.
However, if no accident occurs, you have spent an additional RM100 without receiving a claim benefit.
This illustrates the trade-off: you pay a smaller, predictable amount to reduce a potentially larger financial risk.
Note: These figures are illustrative and assume one eligible accident with no excluded damage or additional fees. Actual excess amounts, protection prices and charges depend on the rental agreement.
What Is Not Covered by Car Rental Insurance?
Standard rental protection may exclude certain types of damage or incidents. Depending on the agreement, you could be responsible for the full repair cost, related fees or other losses.
Common exclusions include:
1. Flood Damage
Flood damage is not automatically included in car rental insurance.
Some Malaysian rental agreements specifically exclude flood-related damage, making this particularly important when travelling during the Northeast Monsoon.
Before renting, ask whether flood protection is included or available separately.
2. Tyres, Windscreens and Undercarriage
Damage to tyres, wheels, windscreens and the vehicle’s underside may be excluded or subject to separate protection.
For example, a damaged tyre caused by hitting a pothole might not qualify under standard CDW.
3. Negligence and Unauthorised Driving
Insurance protection may become invalid if you breach the rental agreement.
Common examples include:
- Driving under the influence of alcohol or drugs.
- Allowing an unauthorised person to drive.
- Participating in racing or prohibited activities.
- Driving outside permitted areas.
4. Missing Accessories and Interior Damage
Lost keys, missing accessories, damaged upholstery and excessive cleaning requirements may result in additional charges.
5. Administrative and Loss-of-Use Charges
Some rental companies impose fees when a damaged vehicle cannot be rented to other customers during repairs.
These charges are not necessarily covered by standard insurance or excess reduction packages.
Even zero-excess protection does not automatically mean every possible expense is covered.
Always review the exclusions before collecting your rental car.
How Much Does Car Rental Insurance Cost in Malaysia?
The cost depends on the rental company, vehicle category and level of additional protection purchased.
Some companies include basic insurance and CDW in their rental rates, while optional upgrades cost extra.
For example, Avis Malaysia’s published General Information page lists:
- CDW excess amounts ranging from RM500 to RM2,000, depending on the vehicle group.
- Windscreen protection at RM5 per day, although availability should be confirmed because other published Avis information differs.
- A Vehicle Cover Plus package at RM30 per day, which can reduce the excess to zero for certain eligible risks.
These are examples from one operator’s published terms, not industry-wide prices. Other Avis information lists different excess amounts and protection arrangements.
Actual charges, availability and exclusions may differ. Always confirm the applicable figures directly with the rental company before booking.
Insurance costs can also vary according to:
- Vehicle category and value.
- Rental duration.
- Included protection.
- Additional coverage selected.
- Rental company policies.
When comparing prices, consider both the rental fee and your potential liability.
A cheaper rental may not offer better value if its excess is significantly higher.
Is Additional Car Rental Insurance Worth Buying?
Additional car rental insurance is worth considering when the cost of reducing your excess is reasonable compared with the financial risk you would otherwise face.
However, extra protection is not necessary for every rental.
| Your Situation | What to Consider |
| Short rental with a low excess | Standard coverage may be sufficient |
| Long-distance road trip | Consider additional excess protection |
| Driving during monsoon season | Check flood exclusions carefully |
| Renting an expensive vehicle | Review the potentially higher excess |
| Existing travel insurance | Check for overlapping rental protection |
When Additional Protection Makes Sense
Consider upgrading when:
- The standard excess is higher than you could comfortably afford.
- You are travelling long distances on unfamiliar roads.
- The upgrade significantly reduces your financial liability.
- You prefer a predictable rental expense.
When You Might Not Need It
Additional protection may be unnecessary when:
- Your existing rental package already offers a low excess.
- You have verified suitable alternative insurance.
- The upgrade provides little additional protection.
- Important risks remain excluded despite the upgrade.
Remember that paying for extra insurance does not guarantee financial savings. Its purpose is to reduce your exposure if an eligible incident occurs.
Read More: Why Car Rental is Important When Traveling in Malaysia
What Should You Check Before Renting a Car in Malaysia?
Before confirming your booking, ask the car rental company these questions:
- Is basic motor insurance included in the rental price?
- Does the package include CDW and Theft Protection?
- What is the maximum excess payable for each accident or damage incident?
- Are flood damage, tyres and windscreens covered?
- How much does additional excess protection cost?
- Are there administrative fees or loss-of-use charges?
- What happens if another authorised driver causes an accident?
- What documents and reports are required if an accident occurs?
Also, distinguish between the security deposit and insurance excess.
A security deposit is money held or pre-authorised under the rental agreement. An excess is the amount you may need to pay for eligible damage.
For example, an RM800 security deposit does not necessarily mean your maximum accident liability is RM800.
What Should You Do If Your Rental Car Gets into an Accident?
If an accident happens, prioritise safety, contact the rental company and follow the required reporting procedures.
Here are five steps to follow.
1. Make Sure Everyone Is Safe
Move to a safe location where possible and seek emergency assistance if anyone is injured.
2. Document the Accident
Take photographs of vehicle damage, road conditions, registration numbers and the surrounding area.
Record the incident’s location and time.
3. Contact the Rental Company
Notify the company immediately and follow its instructions regarding towing, repairs and replacement vehicles.
Avoid arranging repairs independently without approval.
4. Lodge a Police Report
Under Section 52 of the Road Transport Act 1987, drivers generally must report road accidents to the police as soon as reasonably practicable and within 24 hours.
Since 1 August 2025, the Road Transport (Exemption) Rules 2025 have allowed online reporting for certain qualifying incidents involving private vehicles. These include incidents causing damage or injury to an animal, or incidents that do not cause damage or injury to people, other vehicles or property.
However, this limited exception does not automatically apply to rental vehicles.
Rental companies may also require a police report within 24 hours to maintain eligibility for damage protection.
To avoid complications, contact your rental company immediately and follow its reporting instructions. Where required, lodge a report at the nearest police station within 24 hours.
You can refer to the official Road Transport Act 1987 and Road Transport (Exemption) Rules 2025 for the relevant requirements.
Failing to meet reporting conditions may also affect your rental protection.
5. Confirm Your Financial Liability
Ask the rental company to explain the applicable excess, additional charges and required supporting documents.
Request an itemised breakdown of any amount deducted from your deposit or charged separately.
Understand Your Coverage Before You Drive
Car rental insurance in Malaysia provides important financial protection, but the coverage depends on the policy and rental agreement.
Before buying additional insurance, compare the excess, exclusions and upgrade costs. Choose protection that matches your driving plans and financial circumstances.
If you’re comparing rental providers, browse car rental Malaysia business listings on Listing.my and contact providers directly to confirm rental prices, insurance coverage and vehicle availability.
Disclaimer: This article provides general information only and does not constitute legal, financial or insurance advice. Always refer to your rental agreement, insurance policy and the applicable legal requirements.
Sources
- Ministry of Transport Malaysia. Road Transport Act 1987 (Act 333). Sections 52, 90 and 91, covering accident reporting and compulsory third-party insurance.
- Attorney General’s Chambers Malaysia. Road Transport (Exemption) Rules 2025. Effective 1 August 2025, covering limited online accident-reporting exemptions.
- Persatuan Insurans Am Malaysia (PIAM). Motor Insurance Types and Coverage. Explains Act cover, third-party insurance, comprehensive insurance and optional protection.
- Avis Malaysia. General Information. Published rental protection, excess amounts, package prices and exclusions.
- Avis Malaysia. Frequently Asked Questions. Additional details on CDW, excess reduction and windscreen protection.
- Budget Malaysia. Rental Terms and Conditions. Damage waivers, driver restrictions, exclusions and related charges.
- Europcar Malaysia. Terms and Conditions. Insurance excess, deposits, damage waivers, claims requirements and additional charges.
Frequently Asked Questions About Rental Car Insurance in Malaysia
Can I Rent a Car in Malaysia Without Buying Extra Insurance?
Yes, if the rental company permits it. The vehicle must still have legally required motor insurance. Some companies include CDW in their rental rates or require certain protection packages under their rental terms.
Does My Personal Car Insurance Cover a Rental Car?
Not automatically. Personal motor insurance normally covers the specified insured vehicle and permitted uses. Check directly with your insurer before assuming your policy extends to a rented vehicle.
Does Car Rental Insurance Cover Scratches and Dents?
It depends on your coverage. Eligible accidental scratches and dents may fall under CDW, subject to an excess. Exclusions and rental agreement conditions can affect whether you must pay.
Do I Have to Pay the Excess if the Accident Wasn’t My Fault?
Possibly. Some rental companies require an initial excess payment regardless of fault. Reimbursement may be available after liability is established, depending on the company’s terms and claims process.
Does Zero-Excess Car Rental Insurance Cover Everything?
No. Zero-excess protection normally applies only to specified eligible incidents. Excluded damage, negligence, lost accessories and certain administrative charges may still result in additional costs.
Is Flood Damage Covered by Car Rental Insurance in Malaysia?
Not necessarily. Some rental agreements specifically exclude flood damage. Check whether flood protection is included, available as an optional upgrade or excluded entirely before booking.