Financing New Cars vs Used Cars in Malaysia
Key Takeaways
- Used car financing often has higher interest rates, but smaller loan amounts can reduce overall borrowing costs.
- New cars may qualify for longer financing tenures, while used car eligibility depends partly on vehicle age.
- Longer loan tenures reduce monthly instalments but increase total interest costs.
- Malaysia’s Hire-Purchase (Amendment) Act 2026 introduces reducing-balance financing and clearer interest-rate comparisons.
- Compare effective interest rates, deposits, monthly instalments and total repayment before signing.
Buying a new or used car in Malaysia involves more than comparing selling prices. New cars often receive lower financing rates, while used cars can cost less overall because you borrow a smaller amount.
For example, a RM55,000 used car might look more affordable than a new RM80,000 model. But what happens when banks offer different interest rates and repayment periods?
Here is how new and used car financing compares in Malaysia, including bank rate examples and repayment calculations.
New Car vs Used Car Financing: What Are the Differences?
The main differences between new and used car financing are interest rates, loan eligibility, deposit requirements and repayment tenure.
| Financing Factor | New Car | Used Car |
| Interest rate | Often lower | Often higher |
| Maximum financing | Up to 90% under standard packages | Up to 90%, subject to lender and vehicle |
| Loan tenure | Up to 9 years | Up to 9 years, depending on vehicle age |
| Down payment | Commonly at least 10% | May exceed 10% |
| Approval | Based on income, credit and commitments | Same factors, plus vehicle age and valuation |
| Total borrowing | Often higher | Often lower |
For example, Maybank’s main Hire Purchase/-i product offers financing of up to 90% for new and eligible secondhand passenger vehicles, with a maximum tenure of 108 months.
However, financing limits vary by package. Approval may also depend on your income, credit profile and the vehicle’s age.
The takeaway: A new car may have cheaper financing per ringgit borrowed, but that does not automatically make it cheaper overall.
Are Interest Rates Higher for Used Car Loans in Malaysia?
Generally, yes. Malaysian banks commonly charge higher financing rates on used cars because vehicle age, valuation uncertainty and resale risk can affect lending decisions.
However, there is no universal interest rate for every new or used car.
Actual New vs Used Car Financing Rates
CIMB publishes the following indicative effective interest rates (EIR) for passenger vehicles.
| Vehicle Category | New Car EIR | Used Car EIR |
| National passenger car | 6.75% | 8.15% |
| Foreign passenger car | 5.10% | 7.40% |
Source: CIMB Auto Financing Interest Rates, accessed November 2026. Figures are indicative annual effective rates, not guaranteed individual offers.
For foreign passenger vehicles, the difference is 2.30 percentage points.
What Determines Your Interest Rate?
Banks may consider:
- Credit history and repayment behaviour.
- Monthly income and existing commitments.
- Vehicle age, make, model and valuation.
- Down payment and financing amount.
- Repayment tenure.
- Fixed-rate or variable-rate financing.
Even two used cars advertised at similar prices could receive different financing terms.
The takeaway: Compare the rate actually offered by the bank, not just the advertised rate.
How Much Does It Cost to Finance a New Car vs a Used Car?
A used car can have a higher interest rate yet still produce a lower total financing bill. The most useful comparison is the amount borrowed, monthly instalment and total repayment.
Consider two hypothetical vehicles:
- New car: RM80,000
- Used car: RM55,000
Both buyers pay a 10% deposit. The calculations use CIMB’s published indicative annual EIR figures for foreign passenger cars.
New vs Used Car Loan Repayment Example
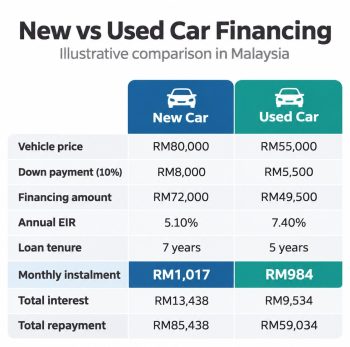
Illustrative reducing-balance calculations using monthly rates equivalent to the stated annual EIRs, rounded to the nearest ringgit. Actual bank quotations may differ. Excludes insurance, road tax, fees and maintenance.
What Do These Figures Tell Us?
Despite the used car’s higher financing rate, its monthly instalment is approximately RM33 lower.
More importantly, the used car buyer:
- Borrows RM22,500 less.
- Pays approximately RM3,904 less interest.
- Completes repayments two years earlier.
- Spends approximately RM28,904 less on the combined deposit and loan repayments.
The monthly difference is relatively small because the used car has a shorter financing tenure.
The takeaway: A higher interest rate does not necessarily mean higher total interest. The financing amount and repayment period matter just as much.
How Does Loan Tenure Affect Your Monthly Instalments?
A longer car loan reduces your monthly instalment but increases the total interest paid.
For example, consider the same RM49,500 used car financing amount at an illustrative 7.40% annual effective rate.
| Financing Tenure | Monthly Instalment | Total Interest |
| 5 years | RM984 | RM9,534 |
| 7 years | RM751 | RM13,582 |
Extending the repayment period from five to seven years reduces the monthly instalment by approximately RM233.
However, you pay approximately RM4,047 more in interest.
Why Do Older Used Cars Sometimes Receive Shorter Loans?
Banks consider a used vehicle’s age when determining financing eligibility.
An older car may receive:
- A shorter maximum repayment tenure.
- A lower financing margin.
- A higher deposit requirement.
- More restrictive financing conditions.
Consequently, a cheaper used car could have a surprisingly high monthly instalment if the bank limits its financing period.
The takeaway: Choose the shortest tenure you can comfortably afford while maintaining sufficient savings for unexpected expenses.
How Much Down Payment Do You Need?
For standard Malaysian hire-purchase arrangements, buyers commonly prepare at least 10% of the vehicle’s purchase price.
However, used car buyers may need a larger deposit if the bank approves a lower financing margin.
Example: Financing a RM50,000 Used Car
| Financing Margin | Deposit Required | Loan Amount |
| 90% | RM5,000 | RM45,000 |
| 85% | RM7,500 | RM42,500 |
| 80% | RM10,000 | RM40,000 |
| 75% | RM12,500 | RM37,500 |
Another consideration is the bank’s valuation.
Suppose a used car dealer advertises a vehicle for RM50,000, but the bank values it at RM45,000.
If the bank finances 85% of its assessed value:
- Maximum financing: RM45,000 × 85% = RM38,250
- Required upfront payment: RM50,000 − RM38,250 = RM11,750
You would need RM11,750 upfront, excluding additional purchase costs, assuming the bank uses its assessed value as the financing basis.
The takeaway: Ask the bank how much it will actually finance before paying a non-refundable booking fee.
What Changed Under Malaysia’s Hire-Purchase (Amendment) Act 2026?
Malaysia’s Hire-Purchase (Amendment) Act 2026 took effect on 1 June 2026, introducing changes to financing calculations and consumer protections.
Bank Negara Malaysia confirmed a transition period until 31 March 2027, allowing financial institutions time to update their systems.
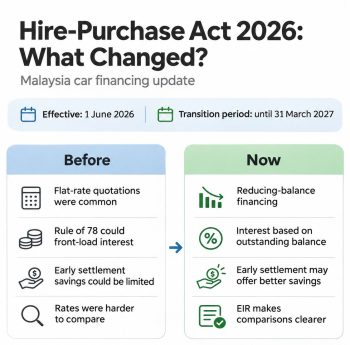
Reducing-Balance Financing vs the Rule of 78
The revised framework moves towards calculating financing charges based on the outstanding loan balance and using effective interest rates for clearer comparisons.
| Previous Framework | New Framework |
| Flat-rate quotations were common | Effective interest rates improve comparisons |
| Rule of 78 could front-load interest allocation | Interest is calculated on outstanding balances |
| Early settlement savings could be limited | Early settlement may offer greater savings |
| Advertised rates were harder to compare | EIR provides clearer cost information |
For example, Maybank adopted reducing-balance financing for its hire-purchase products from 1 August 2026.
However, existing agreements do not automatically switch to the new calculation method. Borrowers with eligible older Rule of 78 agreements may qualify for goodwill discounts when settling early, subject to lender conditions.
Before signing, ask whether your quotation uses reducing-balance financing, what EIR applies and how early settlement will be calculated.
For further information, refer to Bank Negara Malaysia’s official Hire-Purchase Amendment consumer guide.
The takeaway: Compare effective interest rates and actual repayment schedules, particularly during the transition to the revised framework.
Is It Harder to Get Financing for a Used Car?
Not necessarily. However, banks may apply additional restrictions based on the vehicle’s age, condition and assessed value.
Your income and existing financial commitments remain important regardless of which car you choose.
Documents Commonly Required
Applicants should prepare:
- MyKad and driving licence.
- Recent salary slips or income records.
- EPF statements or bank statements.
- Employment confirmation, where required.
- Business registration and financial records for self-employed applicants.
Banks may request additional documentation depending on the applicant and vehicle.
Why Might a Used Car Loan Be Rejected?
Common reasons include:
- Insufficient disposable income.
- Poor repayment history.
- Incomplete income documentation.
- Vehicle age exceeding lender restrictions.
- Asking price exceeding the bank’s accepted valuation.
- Requested loan amount or tenure outside lending criteria.
A lower-priced used car does not guarantee easier approval.
The takeaway: Your repayment capacity and the vehicle’s eligibility both influence the bank’s decision.
Should You Finance a Used Car Through a Dealer or Bank?
Both arrangements can lead to bank hire-purchase financing. The main difference is who coordinates the application.
A used car dealer may submit your application through its panel banks, while approaching a bank directly gives you more control over the enquiry process.
| Financing Route | Potential Advantage | What to Check |
| Used car dealer | Convenient application process | Rates, charges and lender selection |
| Direct bank application | Greater control over enquiries | Vehicle eligibility and documentation |
| Islamic car financing | Shariah-compliant financing | Effective profit rate and contract terms |
| Cash purchase | No financing interest | Remaining savings |
Dealer-arranged financing is not automatically more expensive.
The final cost depends on the lender, approved rate, loan tenure and additional charges.
Request written quotations and avoid arrangements involving artificially inflated vehicle prices to obtain larger loans.
Which Is Better for Your Budget: New or Used Car Financing?
A used car may be the better financing choice when its lower purchase price substantially reduces borrowing costs. A new car may be preferable when its financing terms fit your budget more comfortably.
Choose New Car Financing If:
- You qualify for a competitive effective interest rate.
- You prefer a longer available financing tenure.
- Your income comfortably supports the larger loan.
- The financing package offers better overall value.
Choose Used Car Financing If:
- You want to minimise the amount borrowed.
- You have sufficient savings for the required deposit.
- The vehicle qualifies for a reasonable rate and tenure.
- You prefer to complete repayments sooner.
Before Signing, Check These Five Things
- Down payment: How much cash must you prepare?
- Effective interest rate: What is the actual annual financing rate?
- Monthly instalment: Can you afford it alongside existing commitments?
- Total repayment: How much will you pay throughout the agreement?
- Early settlement: What happens if you repay the financing ahead of schedule?
Remember, a bank’s willingness to approve your loan does not necessarily mean borrowing the maximum amount is financially comfortable.
Is Financing a New Car or Used Car Better?
Financing a used car can save money when its smaller loan amount outweighs the higher interest rate. New car financing, meanwhile, may offer more favourable rates and repayment flexibility.
Compare your deposit, effective interest rate, monthly instalments and total repayment before deciding. Also consider insurance, maintenance and other ownership costs.
If you are comparing automotive-related businesses, you can use Listing.my, our Malaysian business directory, to discover relevant companies and services. Businesses offering automotive and other professional services can also explore our Malaysian business listing services to improve their online visibility.
Disclaimer: This article provides general financial information and illustrative calculations, not personalised financial advice. Actual financing terms depend on lender approval and the applicable agreement.
Sources
- Bank Negara Malaysia — Consumer Guide: Hire-Purchase (Amendment) Act 2026. 17 March 2026.
- CIMB Bank — Auto Financing Interest Rates. Accessed November 2026.
- Maybank — Hire Purchase/-i. Accessed November 2026.
- Maybank — Privilege Hire Purchase. Accessed November 2026.
- AmBank — Banking Industry Hire-Purchase Changes and Early Settlement Discounts. 16 March 2026.
Frequently Asked Questions About New vs Used Car Financing
Can I Get a Nine-Year Loan for a Used Car in Malaysia?
Yes. Some banks offer used car financing for up to nine years. However, eligibility depends on vehicle age, financing amount and lender assessment.
Is Used Car Financing Always More Expensive?
No. Although used car loans often carry higher interest rates, smaller loan amounts can reduce total interest and repayment costs.
Can I Get 100% Financing for a Used Car?
Standard hire-purchase financing commonly requires a deposit. Special financing arrangements may offer higher margins, but availability and eligibility vary between lenders.
Can I Apply for Used Car Financing Without a Dealer?
Yes. You can approach banks directly to enquire about used vehicle financing. The bank will assess your income, creditworthiness and the vehicle’s eligibility.
Does a Larger Down Payment Reduce Car Loan Interest?
Yes. A larger deposit reduces the financing amount, which can lower total interest costs when the rate and tenure remain unchanged.
Can I Settle My Car Loan Early in Malaysia?
Yes. Early settlement is possible, although the settlement amount depends on your financing agreement and calculation method. Eligible older agreements may also qualify for goodwill discounts. Request an official settlement quotation from your lender.